
Learn how credit works and improve your credit score.
Simple financial knowledge designed for working South Africans. Explore practical guides and tools for budgeting credit, and saving.
Budgeting
Learn how to structure your income and control spending.
Credit
Understand how credit works and improve your score.
Saving
Build financial stability and prepare for the future.
Debt Management
Learn how to reduce and control debt.
BUDGETING
Budgeting by Income Band: A Structured Approach to Managing Your Salary
By Moniply Financial Education Team | 8 min read | Budgeting
Most people don’t run out of money because they earn too little. They run out of money because they have no system for managing what they earn. Budgeting by income band is a simple, structured approach that tells you exactly how to split your salary — and it works at every income level.
Why Your Salary Disappears Before Month-End
If your money runs out before payday, you are not alone. Research consistently shows that most South Africans — including middle-income earners — live paycheck to paycheck. The reason is rarely income. The reason is almost always structure.
Without a plan, money flows to the most urgent or visible expenses first: rent, airtime, food — then whatever is left gets spent. Savings and debt repayments become afterthoughts, and by the 20th of the month, the bank account is empty.
Budgeting by income band solves this by giving every rand a job the moment your salary arrives.
What Is Income Band Budgeting?
Income band budgeting means dividing your salary into percentage categories based on how much you earn. The percentages shift slightly depending on your income level — because a person earning R8,000 has less flexibility than someone earning R25,000, even if the categories look the same on paper.
There are four core categories every budget needs:
• Essential expenses — rent, food, transport, utilities, insurance
• Savings and investments — emergency fund, retirement, investments
• Debt repayments — loans, credit cards, store accounts
• Discretionary spending — clothing, airtime, data, entertainment
The Income Band Framework for South Africans
Below is a practical guideline for how to split your salary by income band. These are starting points — your exact split depends on your debt levels, number of dependants, and financial goals.
|
Income Band Category
|
Guideline Allocation
|
|---|---|
|
|
R8 000 – R15 000 | R15 001 – R25 000 | R25 001+
|
|
Essential expenses
|
70–75% | 60–65% | 50–55%
|
|
Savings & investments
|
5–8% | 10–15% | 15–20%
|
|
Debt repayments
|
10–15% | 10–15% | 10%
|
|
Discretionary spending
|
5–10% | 10–15% | 15–20%
|
💡 Moniply Tip
Your Moniply Money Plan automatically applies the right income band percentages to your salary. Log in and complete your profile to see your personalised split.
A Real Example: Thabo’s R12 978 Salary
Let’s look at how income band budgeting works in practice. Thabo earns R12,978 per month. Here is how his Moniply Money Plan structures his salary:
|
Category
|
Monthly Amount
|
|---|---|
|
Essential expenses
|
R8 436 (65%)
|
|
Rent
|
R2 531
|
|
Groceries
|
R2 531
|
|
Transport
|
R2 109
|
|
Utilities (electricity & water)
|
R844
|
|
Funeral policy
|
R422
|
|
Savings & investments
|
R1 298 (10%)
|
|
Emergency saving
|
R441
|
|
Investment
|
R857
|
|
Debt repayments
|
R1 947 (15%)
|
|
Loans / credit card
|
R1 947
|
|
Discretionary spending
|
R1 298 (10%)
|
|
Clothing
|
R908
|
|
Phone / airtime / data
|
R389
|
|
Total
|
R12 978
|
Notice that savings comes before discretionary spending — this is intentional. When you treat savings as a non-negotiable expense rather than ‘what is left over’, you actually save.
The 3 Rules of Income Band Budgeting
Rule 1: Pay yourself first
The moment your salary arrives, move your savings amount into a separate account. Do not wait to see what is left — because nothing will be. Set up an automatic transfer for the day after payday.
Rule 2: Align your billing cycle with your payday
If you are paid on the 25th, set your debit orders and recurring payments to run on the 26th or 27th. This ensures your essential expenses are covered immediately and removes the temptation to spend money that is already allocated.
Rule 3: Review your budget every month — not once a year
Your expenses change. Electricity goes up. A loan gets paid off. A new expense appears. A budget that is not reviewed becomes inaccurate within 60 days. Set a calendar reminder for the last Saturday of every month to update your numbers.
How to Start Today
• Log in to Moniply and complete your profile section
• Your personalised Money Plan will apply the correct income band percentages to your salary
• Set up a separate savings account at your bank (most banks offer free savings pockets)
• Arrange a debit order to transfer your savings amount the day after payday
• Review your plan on the last Saturday of every month
Ready to get your personalised Money Plan?
Moniply builds a budget based on your exact salary and income band. It takes 5 minutes to set up and is free to start. Log in at moniply.co.za and become a Premium Member for personalised Money Plan.
Moniply Financial Education | moniply.co.za | These articles are for general educational purposes and do not constitute financial advice.
Budgeting by Income Band
A structured budgeting approach based on how much you earn.
- What percentage should go to the bills.
- How much you should save.
- How to control lifestyle spending.
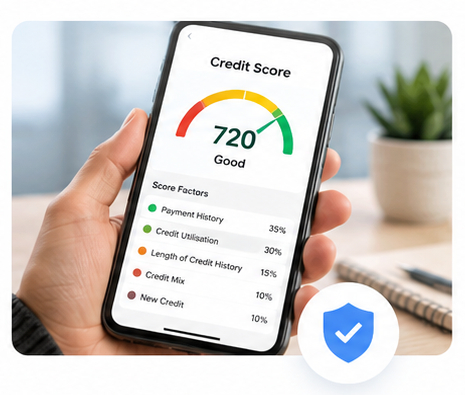
Understanding Credit Scores
Understand how credit bureaus calculate your score.
- Learn :
- What improves your credit score.
- How not to damage your credit profile.
- How to build a stronger credit record.
Emergency Fund Strategy
Learn how to build financial safety for unexpected expenses.
- Learn :
- How much to save.
- Where to keep your emergency fund.
- How to build it even on a tight budget.